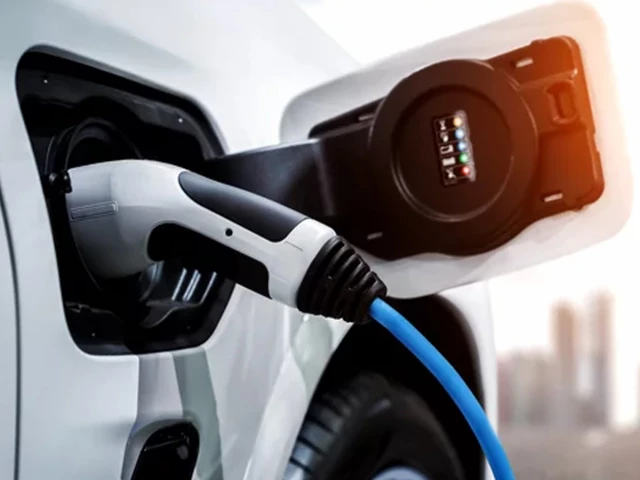
EV boom reshaping local market
Категория: Business
Поделиться
Архив
Нравится
Pakistan's EV future hinges on localisation, not just imported sales
Pakistan's EV future hinges on localisation, not just imported sales
China's automotive industry has set a record this year as vehicle exports have already surpassed last year's total by August. As Chinese automakers expand into emerging markets to offset Western trade barriers and domestic overcapacity, Pakistan has become one of the clearest beneficiaries.
This global push is disrupting a decades-old Japanese auto oligopoly in Pakistan, aided by Islamabad's New Energy Vehicle Policy (NEVP 2025-2030). As Chinese manufacturers expand into high-tech crossovers and electric vehicles, Pakistan stands at a pivotal crossroads: how to leverage Beijing's manufacturing scale to slash its crippling fossil fuel import bill, while avoiding the substitution of one form of import dependence, ie foreign oil, with another: imported batteries, electronics and high-value automotive components.
The central question is, therefore, larger than whether Chinese EVs will displace Japanese cars. It is whether Pakistan can use Chinese technology and capital to move beyond low-value vehicle assembly towards genuine manufacturing, technology transfer, supplier development and eventually exports.
Global supply push
China's total annualised vehicle exports have soared to 12 million units, anchored by 10 million passenger cars. Its new energy vehicle exports, battery electrics and plug-in hybrids combined, have reached an annualised 5.6 million units, eclipsing Japan's historical peak export figures.
This has upended legacy automakers. In just 24 months, Germany's multibillion-dollar trade surplus with China flipped into a deficit. As Western markets impose defensive tariffs, Chinese manufacturers are redirecting capacity towards the Global South. For Pakistan, this creates an unusual opportunity. Chinese firms possess battery, motor, power electronics and software technologies that would take Pakistan decades to develop alone. The challenge is ensuring access that creates domestic productive capacity, not just a bigger market for imported Chinese parts.
Disrupting the 'Big Three'
For over 30 years, Pakistan's car market was dominated by Toyota, Honda and Suzuki, shielded by high tariffs with little pressure to modernise. Macroeconomic headwinds, forex constraints and fuel prices crippled traditional assembly lines, opening the door for new entrants.
Chinese brands, Sazgar Haval, Changan, Chery, BAIC, Jetour, have now captured a share in the SUV and crossover segments, with Haval challenging the Toyota Fortuner. On the electric side, BYD (via Hubco subsidiary Mega Motor Company), Changan's Deepal and budget models like Dewan Honri have pushed EVs from a luxury niche into the mainstream.
This isn't simply China replacing Japan as the market is fragmenting, with Chinese, Japanese and Korean makers competing on price, hybrids, software and financing. Japanese firms retain strong dealer networks and supplier relationships, while Chinese entrants bring faster product cycles and EV capability. The NEVP backs this shift with structure: a target of 30% new energy vehicle sales by 2030, rising to 50% by 2040; 3,000 public fast-charging stations by 2030; a 1-3% carbon levy on combustion vehicles funding EV subsidies; concessional duties on CKD/SKD kits; and a capped charging tariff of roughly Rs40/kWh to absorb surplus power generation.
This matters because Pakistan's electrification push is also an energy-security play. Petroleum imports drain foreign exchange, while the power sector has excess capacity and weak demand. But the net forex benefit depends entirely on how much of the EV value chain Pakistan localises, since a fully imported EV kit assembled locally still increases component imports even as it cuts oil use. Success should be measured in forex savings, domestic value addition, supplier development and exports, not just EV sales volume.
Localisation vs import dependence
The risk is that Pakistan reproduces its old assembly-dependent model with a new technology stack: Chinese tech, imported components and Pakistani final assembly, which is analogous to changing the propulsion system without changing the country's position in the global value chain.
Three factors will determine success. First, manufacturers must be pushed from CKD kit assembly towards local battery manufacturing, parts casting and software integration. This doesn't mean building everything domestically as battery cells and advanced semiconductors need scale that Pakistan can't match. Instead, the policy should target realistic wins: battery-pack assembly, wiring harnesses, castings, plastics, interiors, charging equipment and thermal management.
Secondly, the 3,000-charging-station target needs sustained private investment, grid upgrades and standardised protocols; none of which happen automatically. Low EV penetration makes chargers commercially unattractive, while poor charging infrastructure suppresses adoption – a chicken-and-egg problem. Existing petrol stations could become charging nodes, while battery swapping and fleet charging may matter more for motorcycles, rickshaws and taxis.
Thirdly, Japanese assemblers are introducing their own hybrids to defend their market share, which means more competition that should improve pricing and after-sales service industry-wide.
The bigger opportunity may lie beyond passenger cars. Pakistan's motorcycle, three-wheeler, taxi and commercial-vehicle markets are used intensively and consume heavy fuel, meaning electrification there could deliver faster payback and greater fuel-import savings per rupee of support than premium passenger EVs.
From assembly hub to manufacturing base
The new Automotive Industry Development Policy 2026-31 raises the stakes further, emphasising localisation, investment and exports. The opportunity is to use Chinese manufacturers' search for new markets to strike a deeper bargain: market access in exchange for supplier development, technology transfer, training and export-oriented production.
Pakistan's domestic market alone won't provide the scale for a globally competitive EV industry. The more ambitious goal is integrating Pakistani suppliers into Chinese global value chains and eventually positioning the country as a regional production base. In the end, an exported Pakistan-made component may ultimately matter more than another locally assembled car.
In a nutshell, China has already solved the technological problem of mass EV production. However, Pakistan's challenge is different: capturing a meaningful share of the economic value that EV technology creates. The real story isn't China replacing Japan but whether Pakistan can turn China's automotive rise into a shift from assembling cars for itself to manufacturing products the world wants to buy.
THE WRITER IS A CAMBRIDGE GRADUATE AND WORKS AS A STRATEGY CONSULTANT
Примечание о файлах cookie
Newshunt использует необходимые файлы cookie, чтобы вы оставались авторизованными и чтобы запоминать ваш язык и страну, благодаря чему сайт работает так, как вы ожидаете. С вашего разрешения мы также хотели бы использовать аналитические файлы cookie, чтобы понимать, как люди используют Newshunt, и со временем улучшать его.
Принятие влияет только на аналитику. Подробнее см. в нашей Политике конфиденциальности or Условиях использования.
(0)Комментарии