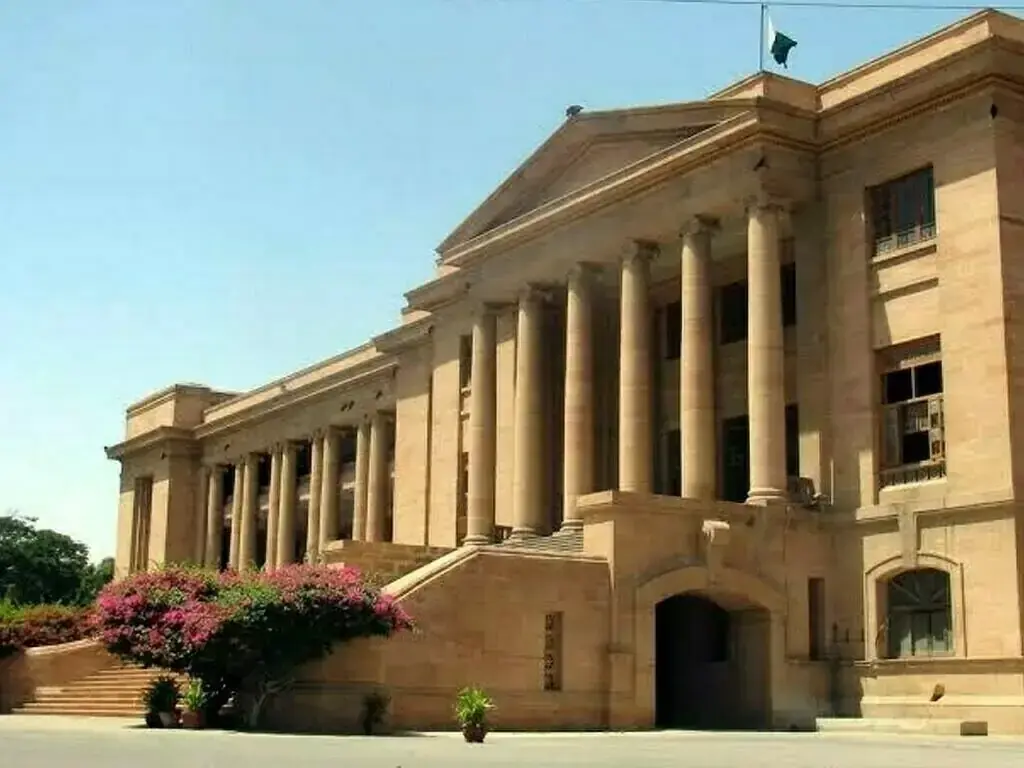
SHC rules a stockbroker liable to pay sales tax in Sindh
Category: Business
Share
Archive
Like
By
ISLAMABAD: The Sindh High Court (SHC) has held that a stockbroker is liable to pay sales tax in Sindh, as the transactions it carries out for its clients are effected through the Karachi Automated Trading System (KATS) in Karachi.
A Division Bench of the Sindh High Court, comprising Justice Mohammad Abdur Rahman and Justice Dr Shah Nawaz Memon, decided two sales tax reference applications filed by Zafar Securities (Pvt.) Limited, a stockbroker based in Lahore.
The effect of the Court's holding is that, from 01.07.2017 onwards, the services of a stockbroker are taxable in Sindh where its trades are executed through the KATS of the Pakistan Stock Exchange, regardless of where the stockbroker or its clients are located.
READ ALSO: FCC order and extraterritorial taxation
The Sindh Revenue Board had raised demands of Rs32.5 million for FY 2016-17 to FY 2020-21, and Rs10.7 million for FY 2021-22 against Zafar Securities.
The company provides its services from its office in Lahore to clients residing in Punjab, Khyber Pakhtunkhwa, and other provinces, and had already paid sales tax on the same services to the Punjab Revenue Authority.
Jahanzeb Sukhera, representing Zafar Securities, argued that the company is resident in Punjab and provides its services in Punjab, and that the same services are already being taxed by Punjab. He also argued that Sindh province cannot tax a person living and working in Punjab and serving clients there, that the same services are taxed by Punjab under the Punjab Sales Tax on Services Act, 2012, and that the levy offends Article 141 and the fundamental rights guaranteed by the Constitution.
The Court held that the Sindh Finance Act, 2017, which came into force on 01.07.2017, amended the definition of 'place of business in Sindh' to include a person who carries on an economic activity 'through virtual presence or a website or a web portal or through any other form of e-Commerce.'
It noted that the transactions that the Applicant (Zafar Securities) effects for its clients are effected through KATS in Karachi: the orders are routed to it, matched on it and executed through it.
The Court; therefore, held that the stockbroker carries on its business, at least in part, from a place of business in Sindh. It also held that the residence of the clients of the stockbroker is irrelevant. However, the Court set aside the demand for the period before 01.07.2017, following its earlier judgment in the Summit Capital case.
The Court did not decide the question of double taxation or whether the levy is valid under Article 141 of the Constitution. It held that these questions could not be determined in its reference jurisdiction.
The judgment observed that the Act of 2011 extends only to the Sindh province and it is the Provincial Assembly that has chosen, through Section 3 read with the amended Section 2 (64), the connecting factor that brings a service within its reach. Whether that connecting factor is a sufficient territorial nexus in terms of Article 141, and how the competing claim of another Province under its own law is to be reconciled, are matters that fall outside the questions arising in these References.
'We express no opinion on them, and nothing said here shall preclude the Applicant from pursuing any remedy available to it in law, including before the appropriate inter-provincial forum,' said the judgment.
Zafar Securities had already approached the National Tax Council (NTC) through an application dated 05.12.2025, seeking a determination as to which province is entitled to tax stockbroker services. Since the NTC did not decide the application, Zafar Securities, through Sukhera, filed a writ petition before the Lahore High Court (LHC).
A Division Bench of the LHC, comprising Justice Muhammad Ajmal Zahid and Justice Hassan Nawaz Makhdoom, directed the NTC to decide the application through a speaking order, after hearing Zafar Securities and all other concerned parties, within a fortnight from the receipt of the order. The NTC is yet to decide the application.
Copyright Business Recorder, 2026
A note on cookies
Newshunt uses essential cookies to keep you signed in and to remember your language and country, so the site works the way you expect. With your permission, we'd also like to use analytics cookies to understand how people use Newshunt and improve it over time.
Accepting only affects analytics. To learn more, view our Privacy Policy or Terms & Conditions.
(0)Comments